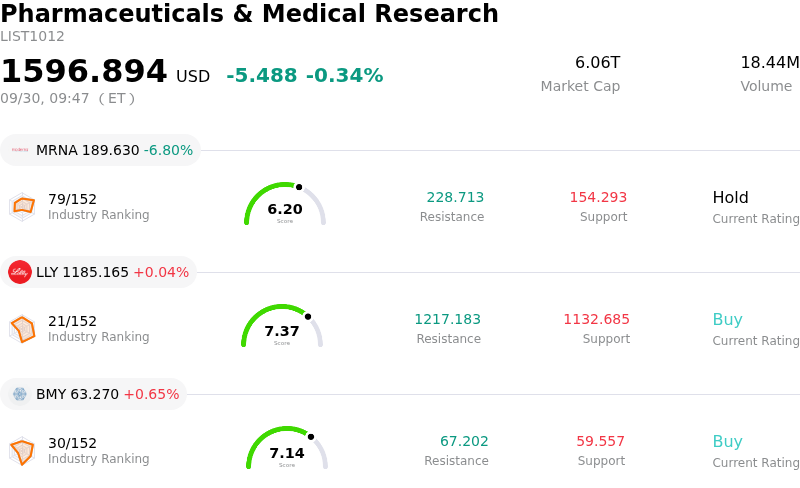
Moderna Inc (MRNA) opened down by 6.27%. The Pharmaceuticals & Medical Research sector is down by 0.34%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Moderna Inc (MRNA) down 6.27%; Eli Lilly and Co (LLY) up 0.04%; Bristol-Myers Squibb Co (BMY) up 0.65%.
What is driving Moderna Inc (MRNA)’s stock price down today?
Moderna experienced sharp selling pressure driven primarily by high-profile sell-side downgrades following a dramatic multi-week rally. Major Wall Street institutions downgraded the biotechnology firm to a Sell rating, flagging that the market value had detached from fundamental realities. Analysts highlighted that the recent stock surge, which was fueled by enthusiasm surrounding clinical trial developments for its personalized mRNA cancer vaccine candidate, had pushed valuation multiples to unsustainable levels. Wall Street research noted that market expectations had priced in broad cross-tumor commercial adoption that far outstripped realistic revenue models and near-term cash flow projections, prompting institutional investors to re-evaluate their exposure.
Compounding the negative valuation sentiment, legal uncertainty reemerged as a major headwind for the company. A Delaware federal court recently denied Moderna's motion to dismiss key claims in ongoing patent infringement litigation concerning foundational mRNA technology. This legal setback introduces litigation risks and potential financial liabilities at a time when the market is scrutinizing the company's financial profile. While the company's pipeline advances, its core operations continue to navigate headwinds from reduced commercial demand for early-generation vaccines, ongoing cash burn, and unprofitability, reinforcing analyst skepticism regarding near-term earnings power.
From a trading dynamics perspective, the decline was further accelerated by profit-taking following a prolonged period of momentum-driven upside. Recent regulatory filings detailing pre-arranged insider stock sales by corporate executives also contributed to a more cautious market stance. As technical momentum cooled, institutional rebalancing and short-term capital harvesting generated significant intraday volatility. Investors are increasingly requiring clear evidence of commercial monetization for pipeline assets rather than speculative valuation premiums, leading to heightened downward pressure on the equity.
Technical Analysis of Moderna Inc (MRNA)
Technically, Moderna Inc (MRNA) shows a MACD (12,26,9) value of 3.905, indicating a buy signal. The RSI at 69.151 suggests neutral condition and the Williams %R at 20.453 suggests buy condition. Please monitor closely.
Media Coverage of Moderna Inc (MRNA)
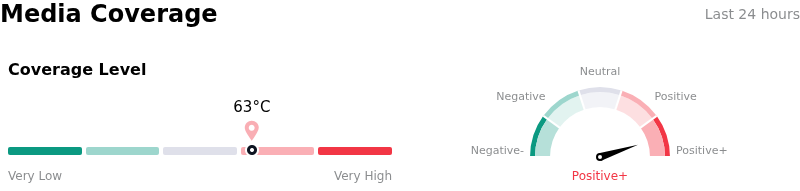
In terms of media coverage, Moderna Inc (MRNA) shows a coverage score of 63, indicating a high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Moderna Inc (MRNA)
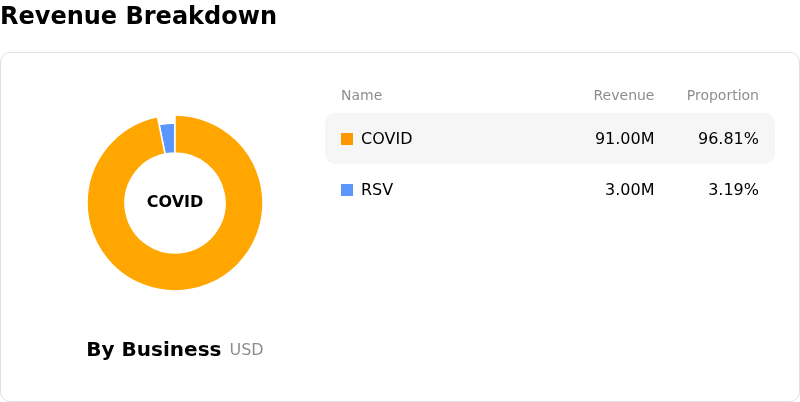
Moderna Inc (MRNA) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $1.94B, ranking 39 in the industry. The net profit is $-2.82B, ranking 195 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $117.66, a high of $170.00, and a low of $40.00.
More details about Moderna Inc (MRNA)
Company Specific Risks:
- Sell-Side Downgrade on Valuation Overreach: Citi downgraded Moderna to "Sell" with an $80 price target, warning that the stock's recent 220%+ rally creates an unjustifiable valuation based on aggressive implied oncology sales of $26 billion for its cancer vaccine intismeran autogene that far exceed net present value models.
- Adverse Federal Patent Litigation Ruling: A Delaware federal court denied Moderna's motion to dismiss a patent infringement lawsuit brought by Bayer's Monsanto division regarding mRNA intellectual property, exposing the company to fresh legal liabilities and potential future royalty burdens.
- Equity Dilution from Upsized Debt Offering: Moderna upsized its offering of convertible senior notes due 2032 to $2.6 billion, raising institutional concerns over potential share dilution upon conversion and increased capital obligations while the company continues to operate with negative net cash flows.
- Execution Hurdles and Distant Commercialization Timelines: Analysts at Leerink and Rothschild Redburn highlight that multi-year regulatory approvals and commercial ramps stand between recent trial milestones and actual top-line revenue, leaving the stock vulnerable to pipeline execution delays and seasonal vaccine revenue volatility.
Find out more