TradingKey - Palo Alto Networks (PANW) closed at $392.09 on September 28, up 4.63% for the day. PANW's revenue growth has been impressive. However, its financials have become more complicated. The gap in PANW’s profitability between GAAP and adjusted numbers has been wide. The strong demand for PANW’s core products and integrated offerings has fueled recent growth, along with the impact of acquisitions. PANW must continue innovating to maintain the momentum in identity security and observe security while adjusting for value-warproppring.
Unit 42 Adds a New AI-Native Security Service
Palo Alto Networks announced Unit 42 Continuous Frontier AI Defense on September 22. The service provides continuous assessment of organization’s systems and provides recommendations for potential security vulnerabilities. The service uses gated frontier models from Anthropic and OpenAI, including Claude Mythos 5 and GPT-5.6-Cyber, alongside Unit 42 threat intelligence and expertise.
PAN described its method as the result of 100+ client engagements and 6 months of company work. Announcing a generic AI framework gives very little information to evaluate the offering. PAN did not release any signed contracts or sales for this service. Enhancing its strategy to offer AI workflows was positive, and management showed investors where it believes the product’s greatest value potential. The financial impact of this product will require further evaluation in future reports.
Console Adds More Agentic Workflows to Cortex
PAN acquired Console on September 1. Console is an AI software platform to implement agent-based AI in enterprise software. PAN will use the technology to advance agentic capabilities to Cortex. The acquisition improved PAN’s AI automation, and according to management, Console and the recently closed Embrace acquisition are immaterial to the company’s fiscal 2027 guidance. The deal does improve PAN’s product capabilities, but investors should not expect its near-term revenueStreams would be impacted by the deal.
FY2026 Growth Was Strong, but Acquisitions Matter
Palo Alto Networks reported a 34% increase in quarterly revenue to $3.41 billion, driven primarily by a 63% increase in Next-Generation Security ARR to $9.10 billion and a 34% increase in remaining performance obligations to $21.20 billion.
Revenue for the year grew from $9.22 billion in FY2025 to $11.48 billion in FY2026.
Although strong from an absolute perspective, these numbers must be analyzed in the context of Palo Alto Networks’ recent acquisitions.
In February 2026, Palo Alto Networks closed the acquisition of CyberArk, which expanded Palo Alto Networks’ security offerings to include identity security. In addition, the acquisition of Chronosphere, completed on January 29, expanded Palo Alto Networks into observability for modern cloud and AI environments.
CyberArk Makes Integration the Central Test
Given the contributions of the acquired businesses, should Palo Alto Networks be required to prove that organic growth would be strong, even after the acquired businesses are included?
In a more refined analysis, CyberArk’s contribution to Palo Alto Networks is a broader identity security offering.
Also in line with Palo Alto Networks’ strategy to offer a broad security platform, integration of CyberArk is expected to increase the company’s identity security platform Idira revenue to approximately $1.5 billion in FY2027, representing high-teens to about 20% pro forma growth.
From a competitive landscape perspective, CyberArk’s identity security offerings complement Palo Alto Networks’ broad security platform.
Chronosphere Added a Large One-Off ARR Boost
Management also noted that the inclusion of nine-figure revenue from the migration of one of their larger AI model customer to Chronosphere during the quarter under review significantly impacted their net new ARR for the period. More precisely, management said the migration of a large AI-model customer added a nine-figure amount to Q4 net new ARR; a smaller remaining contribution is expected in fiscal Q1 2027.
From an investment perspective, I would like to highlight the nature of this additional ARR. Chronosphere's larger customer win is no doubt positive, but from a treatment perspective, this may indicate a larger, more concentrated customer win which the Company may not be able to repeat on a consistent basis.
A more meaningful sign-off going forward may be from customers won after the major migration, and whether or not they will be able to positive impact net new ARR on a more consistent basis.
GAAP Profitability Still Trails Adjusted Results
Palo Alto Networks reported a Q4’2026 GAAP loss of $282 million and $0.35 of loss per share. This was in contrast to a non-GAAP profit of $853 million, or $1.02 per share. The difference between the two sets of numbers was primarily attributed to share-based compensation, acquisition-related costs, amortization of acquired intangibles, a $524 million change in fair value of convertible senior notes and capped calls, litigation items and tax adjustments. While I acknowledge that the non-GAAP figures give a more relevant and long-term focus on the business, stock compensation and other costs associated with integration are real costs and should not be completely ignored. From an equity value and margin focus, a combination of GAAP figures and non-GAAP margins will be more relevant.
Cash Flow Remains a Major Strength
Cash generation is much stronger than the GAAP income statement suggests. Operating cash flow reached about $1.4 billion in Q4. For fiscal 2026, adjusted free cash flow reached $4.41 billion, representing a 38.4% margin. That gives Palo Alto Networks substantial flexibility to fund product development, integrate acquisitions and support its broader platform strategy. The strength of cash flow is one of the best arguments for the stock. The main question is whether that cash flow can stay near current levels as acquisition accounting normalizes and integration costs continue.
FY2027 Guidance Sets a High Bar
Palo Alto Networks expects fiscal year 2027 first quarter revenue between $3.300 billion and $3.310 billion. Management also expects NGS ARR for the first quarter between $9.54 billion and $9.56 billion. The company’s management sets an optimistic outlook for the year and expects fiscal year 2027 revenue between $14.10 billion and $14.20 billion, and adjusted EPS between $4.16 and $4.19. For fiscal year 2027, management also expects an adjusted free cash flow margin of about 38 percent. Stock compensation and other costs excluded from management's forecast will likely impact Palo Alto Networks' actual results.
Palo Alto Networks Technical Analysis: PANW Tests $396.70 as Bulls Eye $405.10
Palo Alto Networks (PANW) has recently moved up to $392.09, after a strong bounce from the $368.80 region. Pricing is currently above both the short-term and long-term moving averages, and the rising trendline. The 2-hour chart is bullish, and RSI is at 62, with the signal line at 60. On the 2-hour chart, the moving averages are rising above the $368.80 region.
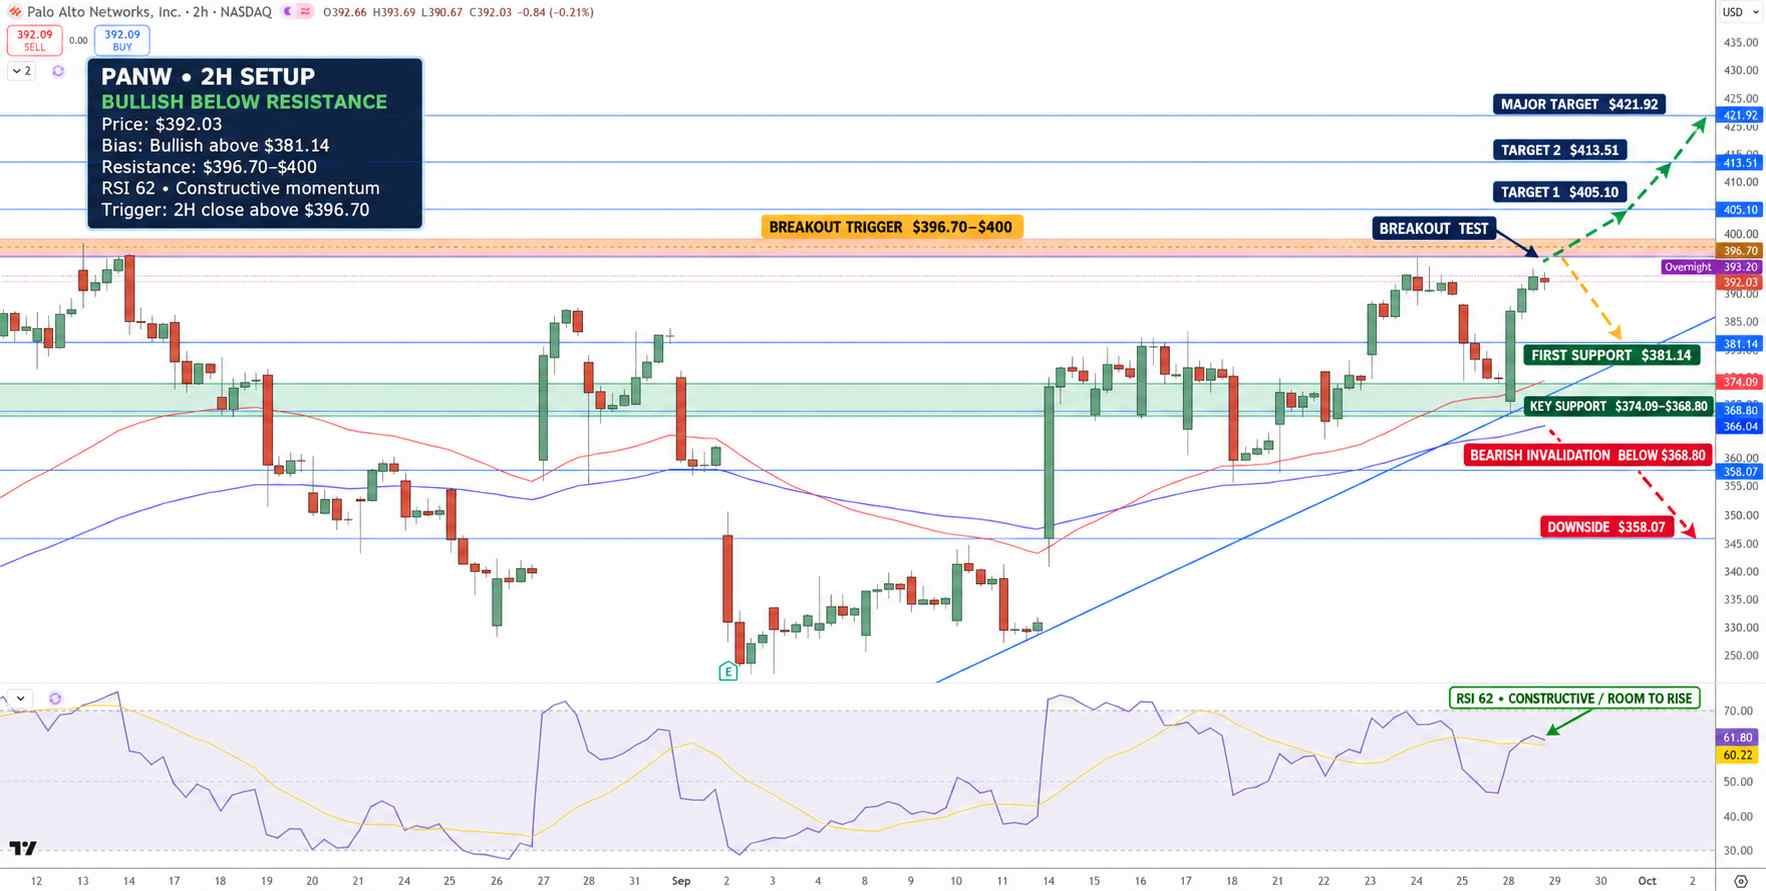
Palo Alto Price Chart - Source: Tradingview
Based on these charts, I am bullish on PANW and would look for long opportunities above $381.14, with an intermediate-term target of $396.70, and an extended target of $405.10. Further out, I would look for resistance at $413.51, $421.92, and $430.23. Support below $381.14 would come at $374.09 and $368.80. A move below $368.80 would negate my bullish view.
Key Levels
• Latest Completed Closing Price: $392.09
• Major Support: $381.14; $374.09 - $368.80; $358.07
• Major Resistance: $396.70 - $400; $405.10; $413.51
• RSI: about 62.
• Breakout Target: $405.10 above a confirmed break of $396.70 - $400.
• Breakout and Stop Levels can change with market conditions. These levels are not to be taken as trade levels.
Why is Palo Alto Networks stock in focus now?
PANW's recent strength is due to strong forward outlook, positive integration and growth updates, and recent launches of new offerings.
What level confirms a stronger PANW breakout?
A sustained 2-hour close above the $396.70 to $400 resistance zone would justify the upside towards $405.10 and later $413.51. If the price breaks support at $381, this setup would weaken its short-term bullish structure.
Bottom Line
Palo Alto has positive growth prospects with a strong expanding customer base in the large-cap cyber security sector. Positive results for new contracts renewals and add-on sales, along with cash flow and CyberArk, support the positive outlook.
The main consideration is the valuation.
Palo Alto Networks trades at approximately 94x the midpoint of fiscal 2027 forecasted adjusted EPS. The company needs to prove the premium is warranted.
Technically, a bullish outlook is in play as long as the stock trades above $381.14. A close above the $396.70 to $400 resistance area would lead to a move to the $405.10 level. The bearish view would take shape on a close below $374.09.
Find out more