TradingKey - Shares of CrowdStrike, Inc. (CRWD) are currently trading at $259.25 per share after rising 2.82% on September 28. It hit a 52 week high of $263.87 on September 24. CrowdStrike is expecting good financial results in the following quarters due to growth in its revenue and free cash flow and due to the recent launches of its security products. Investors will be looking for new security products that the company will be announcing in the future. Most importantly, they will be analyzing the pace at which CrowdStrike achieves its previously set financial targets.
Q2 Showed Strong Recurring-Revenue Momentum
CrowdStrike achieved $1.47 billion in revenue in Q2 of FY2027, a 26% increase from the previous year. The company achieved $1.40 billion in subscription revenues, a 27% increase from the year prior. The company’s ending annualized recurring revenue (ARR) was $5.84 billion, a 25% increase. Net new ARR was $332.8 million, a 51% increase from the year prior. The fast pace at which CrowdStrike increases its new recurring revenue streams illustrates that the company is able to attract and retain a large base of customers. CrowdStrike’s fiscal Q3 ends October 31, 2026; the company has not yet announced an official Q3 earnings-release date.
Falcon Flex Is Driving Broader Platform Adoption
As an added boost to the growth story, we’re starting to see positive momentum from Falcon Flex. End of period (EOP) Annual Recurring Revenue (ARR) from customers with Falcon Flex embedded in their contracts was more than $2.29 billion, up 101% year-over-year. Growth at this pace indicates that larger customers are standardizing more security workloads on the Falcon platform rather than buying isolated products across multiple vendors. We like this trend, as expanding the customer base to increase and enhance platform adoption increases contract size and acts as an impediment to customer platform churn.
From an investment perspective, the strongest testimony to this strategy would be conversion to new, net ARR. From a customer expansion perspective, the strongest evidence in favor of Falcon Flex would be increased contracts, and expanded and renewed contracts.
Free Cash Flow Remains a Major Strength
CrowdStrike’s Q2 free cash flow (FCF) was approximately $377 million, up from approximately $284 million year-over-year. Cash flow from operations for the quarter was approximately $530 million. Cash and cash equivalents at the end of the quarter were approximately $5 billion. The flexible sheet cash flow nature of the business allows management to strategically fund the growth of the business. I believe, from an investment perspective, free cash flow is the strongest of the business’s many positives.
While the expansion in the business is heavily funds from operations and cash flow, FCF was much higher than GAAP net income of $5.3 million and also above non-GAAP net income of $322.9 million. From an investment perspective, the combination of strong free cash flow and improving GAAP profitability is a strong positive for the business.
GAAP Profitability Is Improving, but Stock Compensation Matters
CrowdStrike posted a big improvement in its second quarter FY2027 financial results, reporting GAAP net income of $5.3 million, compared to a loss of $70.2 million in Q2 FY2026. However, the difference between CrowdStrike’s GAAP and adjusted (or “non-GAAP”) net income is still large. For Q2 FY2027, stock-based compensation and related payroll tax expenses were approximately $399 million. Of course, these expenses are not completely ignored. Stock-based compensation is a non-cash expense that helps preserve cash but can dilute existing shareholders as awards vest; the $334 million April 2021 “stock-based compensation financing round” described previously was not a CrowdStrike financing event. I’d focus on Cash Flow, Dilution and other financial fundamentals, in addition to potential market disruptions.
Falcon Guardian Opens a New AI Security Market
The introduction of Falcon Guardian at Fal.Con provides CrowdStrike a first-mover advantage in a large market opportunity. The market is large because enterprises are adopting AI agents, and Falcon Guardian enables control over those agents. Like other Falcon products, Falcon Guardian is likely to provide an opportunity for additional revenue. As Falcon Guardian is added to the platform or purchased via Falcon Flex, the company will develop a baseline for future offerings. Falcon Guardian provides an additional control point for CrowdStrike’s product lock-in strategy.
OpenAI and NVIDIA Expand the AI Opportunity
OpenAI announced several improvements to its services this week. For CrowdStrike, CrowdStrike and OpenAI expanded their partnership to secure Codex agents with Falcon Guardian and bring GPT-5.6 Cyber to defensive workflows on the Falcon platform. In addition, CrowdStrike’s recently launched SafeMind cybersecurity family of models also leverages NVIDIA Nemotron technology. From an investor perspective, the focus remains on customer acceptance of the company’s AI products as well as expansion of existing AI customer contracts. Raising the number of AI partnerships without positive impact on sales will likely have minimal impact on CrowdStrike’s valuation.
The July 2024 Incident Still Has Residual Effects
According to CrowdStrike’s latest Form 10-Q, negative effects of the software incident that occurred in July 2024 continue to impact CrowdStrike’s business. This incident has increased the length of time it takes CrowdStrike to close a sale, and when a sale is closed, it takes even longer for the customer to make a purchasing decision. Customer commitment packages introduced after the incident have included discounts, additional modules, professional services, flexible payment terms and subscription-period extensions. CrowdStrike says these packages have increased contraction because of longer subscription terms and reduced upsell dollar values. These customer agreement changes were implemented after the incident in July 2024. There is evidence to suggest CrowdStrike's recent strong performance may be short lived.
Guidance Raises the Bar
Management increased the expected 2027 full year net new ARR growth to approximately 34% compared to the previous expected range of 31% to 33%. For Q3, expected revenue is between $1.523 billion to $1.529 billion, and expected ending ARR is between $6.184 billion to $6.188 billion. The expected range for the full year is between $5.991 billion to $6.011 billion in revenue, $6.603 billion to $6.612 billion ending ARR and a non-GAAP EPS of $1.25 to $1.26. Management guidance is generally considered the bar for the company. For the current quarter I would focus on the impact to ending ARR and net new ARR as well as free cash flow, and to a lesser extent, EPS.
Valuation Leaves Little Room for Slower Growth
In the recent market close on September 28, 2026, CrowdStrike’s market cap was $266 billion. Using the mid-point of management’s 2027 revenue guidance, CrowdStrike trade for approximately 44 times expected revenue. From a valuation perspective, the stock is extremely risky. At $259.25, it trades approximately 206 times the midpoint of expected non-GAAP EPS. Given the valuation, a modest deceleration to revenue growth creates substantial risk to the stock. Focus should be on ongoing operations.
CrowdStrike Technical Analysis: CRWD Holds $247.07 Breakout as Bulls Target $264
CrowdStrike Inc. (CRWD) recently broke above resistance at $247.07, and the bulls are now targeting a move to $264. On September 2, the CRWD stock closed at $203.42, and after a strong uptrend, closed most recently at $259.25. After the break above resistance at $247.07, CRWD stock pulled back to the breakout level.
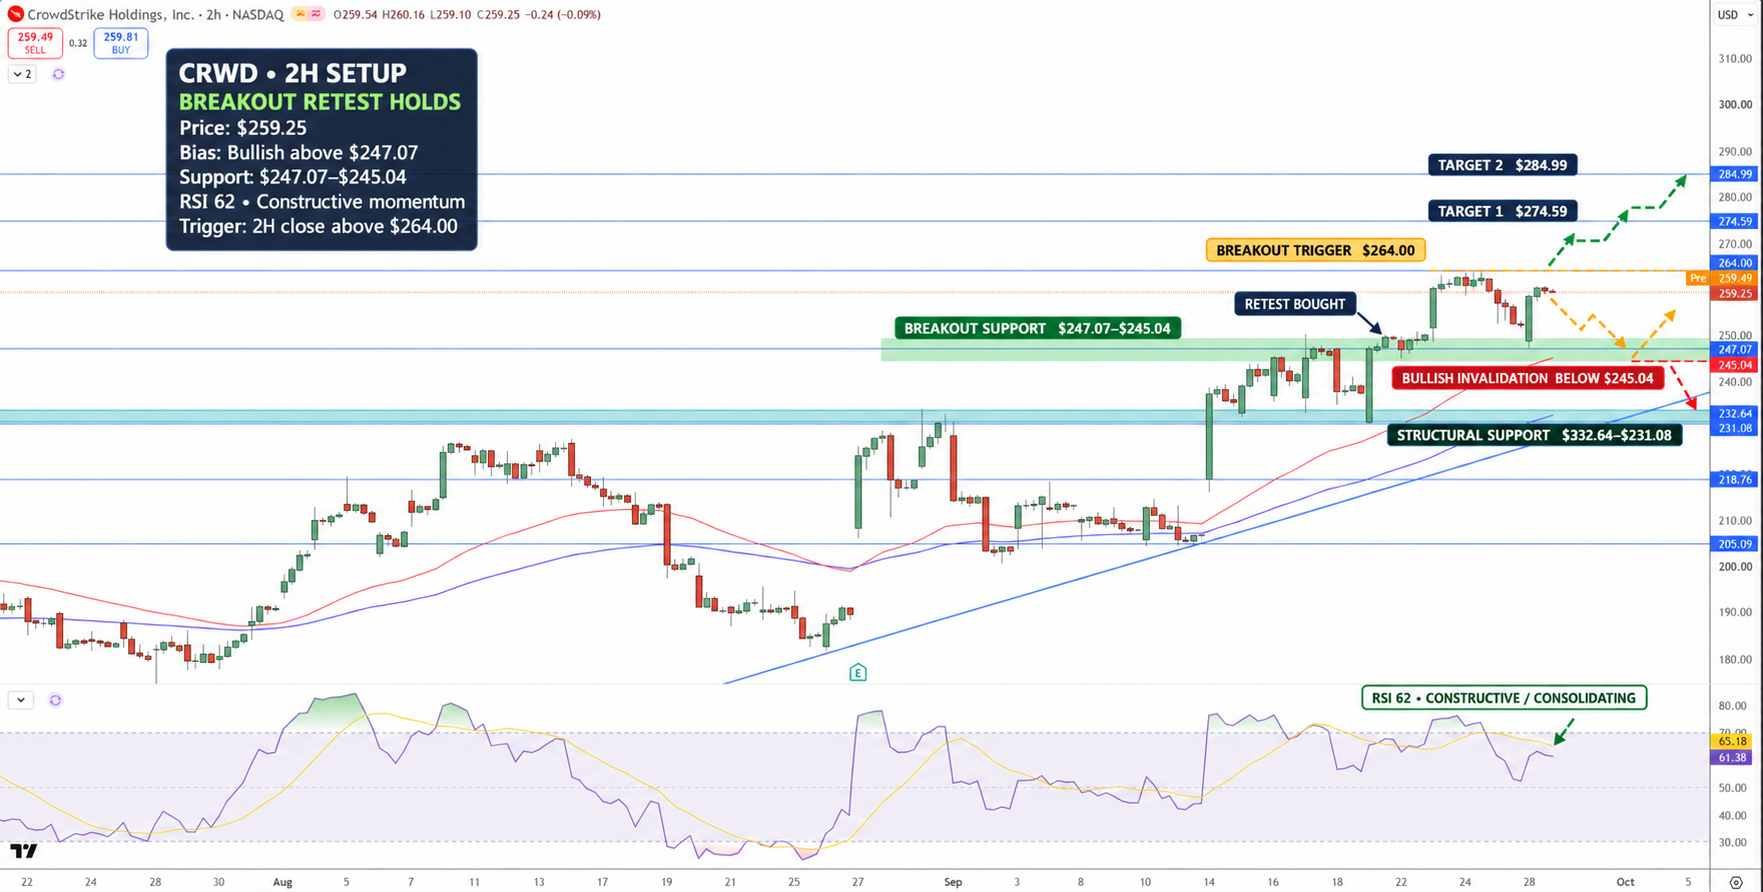
CrowdStrike Stock Price Chart - Source: Tradingview
When a stock pulls back to the breakout level, it is often seen as a bullish sign, and may indicate that the level is now support. The Relative Strength Index (RSI) of CRWD is at about 62, below its signal line near 65, showing bullish momentum that has cooled from overbought conditions.
The resistance level at $264, is expected to be tested in the near future. A break above $264 would put the next level of resistance at $274.59, and then $284.99. If CRWD tests and breaks below the $247.07 to $245.04, the bullish outlook would be negated, and support would shift to the $232.64 to $231.08 level. I am bullish on CRWD as long it trades above $247.07, and would expect it to rise to $264 in the near-term.
Why is CrowdStrike stock in focus now?
CrowdStrike's most recent news indicated that net new ARR was growing, and the company had launched a new service and expanded in other areas. Falcon Flex is rapidly gaining customers. Additionally, the company announced efforts to use Artificial Intelligence in security, most notably with their partnerships with OpenAI and NVIDIA.
What level confirms a stronger CRWD breakout?
I expect further upside to the $264 area. A close above that level would indicate further upside to the $274 area. A close below the $245 area would be bearish.
Bottom Line
CrowdStrike is an innovative company and a leader in the field. The company's focus on ARR and free cash flow strengthens the case even more so. With the recent increase in the stock price, the valuation is moving toward an extreme level.
Trading at roughly 206 times guided non-GAAP earnings, and 44 times guided sales, the company must continue to report impressive earnings in order to justify the valuation.
Due to the recent rally in the stock price, CrowdStrike is still bullish in the near-term, but a break below the $247.07 to $245.04 support zone would weaken the bullish structure materially. A break above $264 would further validate the bull case.
Find out more